
It's often been said that you can choose your friends but you can't choose your family. I don't think that's meant to be complimentary to family!
Having said that, engaging family members as financial partners in a property development project can be a tempting idea. I often talk about how important it is for money partners to know, like and trust you, and who fits that definition better than family?
Let's take a look at the pros and cons of involving family members in your property development project.
I'll start by being very clear - navigating family dynamics while pursuing financial goals requires careful planning and communication. This is not something you should go into lightly.
After all, how is Christmas dinner going to work if some or all of your relatives hate you for stuffing up and losing mum and dad's house? Not pretty.
Having said that, you could also be anointed the golden child if things go well. Okay, now I'm getting cheeky. Parents don't have favourites, right?
Advantages of Involving Family Members
One of the biggest advantages of partnering with family members is the inherent trust that exists between you. This can simplify negotiations and reduce their fear of getting ripped off. They're more likely to share similar values and long-term visions, which can help create a harmonious partnership.
It's possible family members may be willing to invest without the stringent conditions often required by traditional lenders. This can make it easier to secure the necessary funding to launch a project and can help kickstart projects that might be challenging to fund through traditional means.
 Family partnerships can also offer more flexible arrangements in terms of funding arrangements and profit-sharing. This can be crucial when navigating the often unpredictable landscape of property development.
Finally, family members are less likely to impose pressure for immediate returns, allowing for a more patient approach to development. This is particularly the case when you share a common vision such as creating wealth for future generations.
Disadvantages of Involving Family Members
You didn't think it was all good stuff did you? Earlier I touched on the fact that if things go wrong, you're still family.
Things don't even need to go wrong before mixing family and business can lead to emotional conflicts. Disagreements about financial decisions, project direction, or profit distribution can strain personal relationships. It’s vital to establish clear boundaries between family and business roles.
Family members may have differing views on risk, investment strategies, and project goals. These differences can complicate decision-making and potentially stall progress.
You also have to consider the power dynamics in your family. For example, the parents may feel they hold the ultimate authority in family decisions, leading to conflict when you want to take the lead on your project.
These same dynamics can also complicate accountability, with family members hesitating to confront each other about performance issues for fear of rocking the boat.
Remember, too, that while family members may provide capital, they might lack the necessary expertise in property development. This lack of experience can lead to poor decision-making and ultimately jeopardize the project’s success if you defer to them.
In the end, if a project fails, the financial loss can impact not only the project but also personal relationships. It’s essential to have a transparent understanding of these risks before committing.
Structuring the Partnership
If you decide to move forward with family members as partners, it’s essential to establish a clear structure. Sure, they're your family and you (hopefully) love and trust each other, but don't be lulled into a false sense of security. Life has an annoying tendency to happen, and it's at that point you want to know your project is safe.
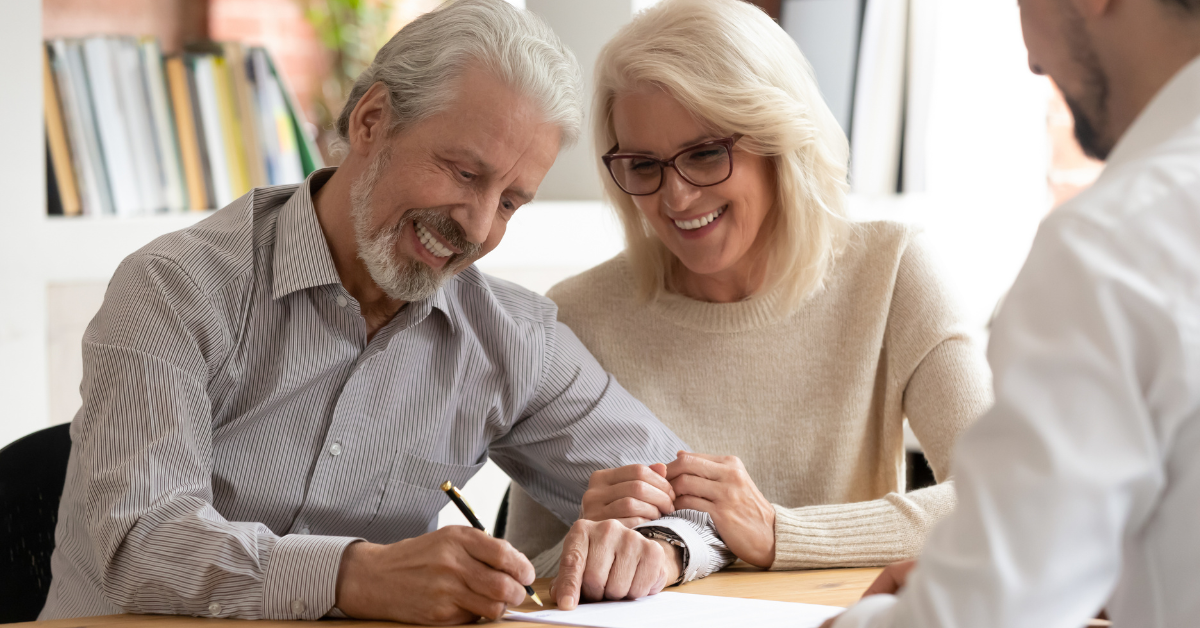
As a starting point draft a comprehensive partnership agreement that outlines each member’s roles, responsibilities, and contributions. This document should cover decision-making processes, profit distribution, and procedures for resolving disputes. A written document will provide clarity and reduce misunderstandings.
Clearly outline the terms of investment, including initial contributions, expected returns, and timelines. It’s also important to discuss how both profits and losses will be dealt with. Setting these expectations upfront can help prevent future disagreements.
If family members want to do more than just contribute money, then assign specific roles based on each family member’s strengths and expertise. For example, designate someone to handle finances, another person for project management, and someone else for marketing. Clearly defined roles can help streamline operations and minimize conflicts.
Finally, develop a plan for what happens if a family member wants to exit the partnership. This should include buyout terms and valuation methods to ensure fairness.
The agreement should also cover what happens if a family member dies. Okay, I know that's not something you want to contemplate when it comes to people you love, but suck it up and discuss it anyway.
 Communication Strategies
Establish regular calls, emails or meetings to discuss project updates, financial performance, and any concerns. Regular communication helps ensure everyone stays informed and can address issues proactively.
Foster an environment where family members feel comfortable expressing their opinions. Open dialogue can lead to better decision-making and strengthen relationships.
If conflicts arise, consider involving a neutral third party to mediate discussions. A professional mediator can help navigate emotional dynamics and guide the family toward resolution.
On a more positive note, recognize and celebrate project milestones together. Whether it’s breaking ground, completing a phase, or making a sale, these celebrations help to strengthen relationships and keep everybody in the loop.
It's also a good idea to encourage family members to educate themselves about property development. Better understanding of the property development process can enhance decision-making and increase the project’s likelihood of success.
Having family involved in your property development journey can be hugely rewarding for everyone, as long as you make the effort to do it in a professional manner. And while I've couched all these strategies in terms of family, in reality these tips basically apply to any money partners you have in your deal.
Ultimately, a well-structured partnership can not only lead to financial success but also strengthen family bonds through shared experiences and achievements.
Having said that, engaging family members as financial partners in a property development project can be a tempting idea. I often talk about how important it is for money partners to know, like and trust you, and who fits that definition better than family?
Let's take a look at the pros and cons of involving family members in your property development project.
I'll start by being very clear - navigating family dynamics while pursuing financial goals requires careful planning and communication. This is not something you should go into lightly.
After all, how is Christmas dinner going to work if some or all of your relatives hate you for stuffing up and losing mum and dad's house? Not pretty.
Having said that, you could also be anointed the golden child if things go well. Okay, now I'm getting cheeky. Parents don't have favourites, right?
Advantages of Involving Family Members
One of the biggest advantages of partnering with family members is the inherent trust that exists between you. This can simplify negotiations and reduce their fear of getting ripped off. They're more likely to share similar values and long-term visions, which can help create a harmonious partnership.
It's possible family members may be willing to invest without the stringent conditions often required by traditional lenders. This can make it easier to secure the necessary funding to launch a project and can help kickstart projects that might be challenging to fund through traditional means.
Family partnerships can also offer more flexible arrangements in terms of funding arrangements and profit-sharing. This can be crucial when navigating the often unpredictable landscape of property development.Finally, family members are less likely to impose pressure for immediate returns, allowing for a more patient approach to development. This is particularly the case when you share a common vision such as creating wealth for future generations.
Disadvantages of Involving Family Members
You didn't think it was all good stuff did you? Earlier I touched on the fact that if things go wrong, you're still family.
Things don't even need to go wrong before mixing family and business can lead to emotional conflicts. Disagreements about financial decisions, project direction, or profit distribution can strain personal relationships. It’s vital to establish clear boundaries between family and business roles.
Family members may have differing views on risk, investment strategies, and project goals. These differences can complicate decision-making and potentially stall progress.
You also have to consider the power dynamics in your family. For example, the parents may feel they hold the ultimate authority in family decisions, leading to conflict when you want to take the lead on your project.
These same dynamics can also complicate accountability, with family members hesitating to confront each other about performance issues for fear of rocking the boat.
Remember, too, that while family members may provide capital, they might lack the necessary expertise in property development. This lack of experience can lead to poor decision-making and ultimately jeopardize the project’s success if you defer to them.
In the end, if a project fails, the financial loss can impact not only the project but also personal relationships. It’s essential to have a transparent understanding of these risks before committing.
Structuring the Partnership
If you decide to move forward with family members as partners, it’s essential to establish a clear structure. Sure, they're your family and you (hopefully) love and trust each other, but don't be lulled into a false sense of security. Life has an annoying tendency to happen, and it's at that point you want to know your project is safe.
As a starting point draft a comprehensive partnership agreement that outlines each member’s roles, responsibilities, and contributions. This document should cover decision-making processes, profit distribution, and procedures for resolving disputes. A written document will provide clarity and reduce misunderstandings.
Clearly outline the terms of investment, including initial contributions, expected returns, and timelines. It’s also important to discuss how both profits and losses will be dealt with. Setting these expectations upfront can help prevent future disagreements.
If family members want to do more than just contribute money, then assign specific roles based on each family member’s strengths and expertise. For example, designate someone to handle finances, another person for project management, and someone else for marketing. Clearly defined roles can help streamline operations and minimize conflicts.
Finally, develop a plan for what happens if a family member wants to exit the partnership. This should include buyout terms and valuation methods to ensure fairness.
The agreement should also cover what happens if a family member dies. Okay, I know that's not something you want to contemplate when it comes to people you love, but suck it up and discuss it anyway.
Communication StrategiesEstablish regular calls, emails or meetings to discuss project updates, financial performance, and any concerns. Regular communication helps ensure everyone stays informed and can address issues proactively.
Foster an environment where family members feel comfortable expressing their opinions. Open dialogue can lead to better decision-making and strengthen relationships.
If conflicts arise, consider involving a neutral third party to mediate discussions. A professional mediator can help navigate emotional dynamics and guide the family toward resolution.
On a more positive note, recognize and celebrate project milestones together. Whether it’s breaking ground, completing a phase, or making a sale, these celebrations help to strengthen relationships and keep everybody in the loop.
It's also a good idea to encourage family members to educate themselves about property development. Better understanding of the property development process can enhance decision-making and increase the project’s likelihood of success.
Having family involved in your property development journey can be hugely rewarding for everyone, as long as you make the effort to do it in a professional manner. And while I've couched all these strategies in terms of family, in reality these tips basically apply to any money partners you have in your deal.
Ultimately, a well-structured partnership can not only lead to financial success but also strengthen family bonds through shared experiences and achievements.