
It's the moment you've been working towards. There's enough profit in the deal that you could maybe keep one of the properties with a mortgage instead of selling them all.
But although you CAN do it, the question is SHOULD you do it. And I'm going to say this right now and get it over with: what follows is my personal opinion only. You should get professional advice for your own situation, as I don't know your personal circumstances.
So let's dig deeper on this...
Look, I get it. You've spent months if not years running a development project from start to finish. If you followed the Property Development Formula process, the project's located in a good area, and designed to suit your target market.
Easy to sell the end stock for the right price, but also very appealing to potential renters. So it's hugely tempting to hang onto one. And if you're currently renting, even more tempting to make one your principal place of residence.
There's one really crucial thing to remember here though - being a Property Developer isn't about one deal. It's a journey that unfolds across a number of deals.
Which means each deal feeds into the next one - experience, debt, borrowing capacity, and more are all impacted by every deal you do.
The idea is to make that effect a positive one, so it's easier to do the next deal, rather than harder. It also means that as you progress along the journey and your situation changes, the potential right answer changes as well.
For now, let's start at the beginning with a small deal. I'm going to talk about deals that involve building, as it's unlikely that you'll look at a patch of earth, fall in love and want to live there. But a shiny new property? Tempting...
Assuming you're following the process, it's likely your first deal will be a small one. Which most likely means turning one property into 2 or maybe 3. It's highly unlikely at that point that there will be enough profit in the deal to make it possible for you to retain one property at the end without a mortgage.
So when you're looking for another deal, you now have a mortgage against your name. Banks are definitely going to take that into consideration when assessing you for a future project - and it's not going to work in your favour.
Diverting from property development for a moment, just ask any buy and hold investor. Even if they're buying cashflow properties, there will come a point where the bank just says "No! You own enough properties!" and turns off the money tap.
For developers, the same thing happens, although I have a suspicion it might happen even earlier, given the risk perception banks have around developers!
One analogy I sometimes use around debt is to think of it like it's a balloon. For your first deal, you blow up the balloon, and when the deal is done and you pay everything out, all the air goes out of the balloon.
Those of you who've looked at a balloon once you let the air out (rather than the much more fun option of popping it!) will know that the balloon never quite goes back to its original shape. It's always a little stretchier.
Which means that the next time you blow the balloon up, it will get bigger. Then you let the air out at the end of the deal, and when it's deflated it's even stretchier than before.
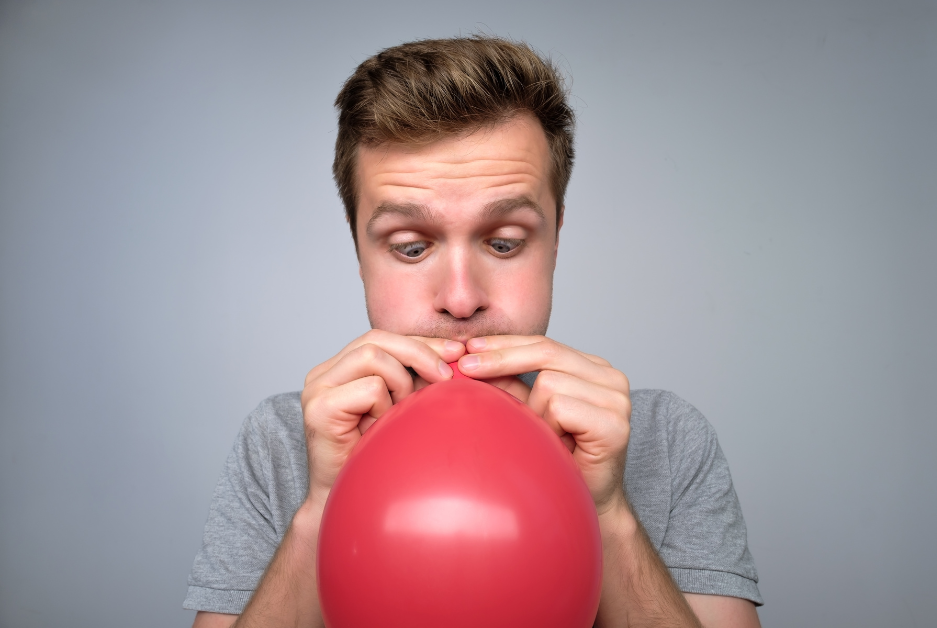
You repeat the cycle of blowing up the balloon (taking on debt) then paying it down (sell off the end product of the project) until eventually you reach the point where there's enough stretch in the balloon left as you're deflating the balloon to allow you to keep one of the properties debt free.
It varies, but in my experience you reach that point around the time when you start creating 6 properties from 1. So when your skills and equity have stretched enough for you to do that, you've reached the point where you're essentially getting a fully paid property for "free".
"Aha!" I hear you cry. "But you're always talking about ways to do no money down deals. Why should I care about getting banks to finance my deals, when I can work with investors or JV partners?" And you're right, but I'm trying to keep it simple in order to make my point.
You keep a property at the end of a project when there's enough profit in the deal for you to keep it debt-free once everything and everyone else is paid out.
So yes, you can use partners to finance deals, but obviously you will have to pay a percentage of your profit to those partners, and that can vary a lot depending on how you've structured the finance.
Which is why I've kept my example simple by pretending you're only going to use your own money and finance.
And look, reality is that the "right" time to keep stock instead of selling it is different for everyone, so I'll reiterate my earlier advice that you should consult a financial professional to assess your own personal situation.
But as a rule of thumb, the earlier you are in your Property Developer journey, the more likely it is that it's too soon to keep stock. Aim for the level of turning 1 property into 6, and that's most likely when you need to start crunching numbers with your advisers to determine if the time to start building your property portfolio has arrived.
But although you CAN do it, the question is SHOULD you do it. And I'm going to say this right now and get it over with: what follows is my personal opinion only. You should get professional advice for your own situation, as I don't know your personal circumstances.
So let's dig deeper on this...
Look, I get it. You've spent months if not years running a development project from start to finish. If you followed the Property Development Formula process, the project's located in a good area, and designed to suit your target market.
Easy to sell the end stock for the right price, but also very appealing to potential renters. So it's hugely tempting to hang onto one. And if you're currently renting, even more tempting to make one your principal place of residence.
There's one really crucial thing to remember here though - being a Property Developer isn't about one deal. It's a journey that unfolds across a number of deals.
Which means each deal feeds into the next one - experience, debt, borrowing capacity, and more are all impacted by every deal you do.
The idea is to make that effect a positive one, so it's easier to do the next deal, rather than harder. It also means that as you progress along the journey and your situation changes, the potential right answer changes as well.
For now, let's start at the beginning with a small deal. I'm going to talk about deals that involve building, as it's unlikely that you'll look at a patch of earth, fall in love and want to live there. But a shiny new property? Tempting...
Assuming you're following the process, it's likely your first deal will be a small one. Which most likely means turning one property into 2 or maybe 3. It's highly unlikely at that point that there will be enough profit in the deal to make it possible for you to retain one property at the end without a mortgage.
So when you're looking for another deal, you now have a mortgage against your name. Banks are definitely going to take that into consideration when assessing you for a future project - and it's not going to work in your favour.
Diverting from property development for a moment, just ask any buy and hold investor. Even if they're buying cashflow properties, there will come a point where the bank just says "No! You own enough properties!" and turns off the money tap.
For developers, the same thing happens, although I have a suspicion it might happen even earlier, given the risk perception banks have around developers!
One analogy I sometimes use around debt is to think of it like it's a balloon. For your first deal, you blow up the balloon, and when the deal is done and you pay everything out, all the air goes out of the balloon.
Those of you who've looked at a balloon once you let the air out (rather than the much more fun option of popping it!) will know that the balloon never quite goes back to its original shape. It's always a little stretchier.
Which means that the next time you blow the balloon up, it will get bigger. Then you let the air out at the end of the deal, and when it's deflated it's even stretchier than before.
You repeat the cycle of blowing up the balloon (taking on debt) then paying it down (sell off the end product of the project) until eventually you reach the point where there's enough stretch in the balloon left as you're deflating the balloon to allow you to keep one of the properties debt free.
It varies, but in my experience you reach that point around the time when you start creating 6 properties from 1. So when your skills and equity have stretched enough for you to do that, you've reached the point where you're essentially getting a fully paid property for "free".
"Aha!" I hear you cry. "But you're always talking about ways to do no money down deals. Why should I care about getting banks to finance my deals, when I can work with investors or JV partners?" And you're right, but I'm trying to keep it simple in order to make my point.
You keep a property at the end of a project when there's enough profit in the deal for you to keep it debt-free once everything and everyone else is paid out.
So yes, you can use partners to finance deals, but obviously you will have to pay a percentage of your profit to those partners, and that can vary a lot depending on how you've structured the finance.
Which is why I've kept my example simple by pretending you're only going to use your own money and finance.
And look, reality is that the "right" time to keep stock instead of selling it is different for everyone, so I'll reiterate my earlier advice that you should consult a financial professional to assess your own personal situation.
But as a rule of thumb, the earlier you are in your Property Developer journey, the more likely it is that it's too soon to keep stock. Aim for the level of turning 1 property into 6, and that's most likely when you need to start crunching numbers with your advisers to determine if the time to start building your property portfolio has arrived.